


By Khairul Khalid
 Petronas’ U-turn in a RM4 billion LNG tankers deal, conceding ownership to subsidiary MISC instead of operating the vessels themselves, is a sign that the oil crisis is forcing Petronas’ hands.
The collapse of crude oil price in the last 12 months is forcing many oil giants (to quote the usual biz speak) “rethink”, “reprioritise” and “reposition” their business plans drastically. Budgets are slashed. Expenditure reduced. Mega projects are postponed or scaled down.
In many cases, some may say that they are eating a long overdue humble pie.
Case in point is the recent move by Malaysia’s state oil company Petroliam Nasional Bhd (Petronas) to transfer ownership of five new liquefied natural gas (LNG) carriers to Malaysia International Shipping Corporation Bhd (MISC).
The carriers will be constructed for an estimated US$1.1 billion (RM4 billion) and are to be delivered to MISC in 2016-2017 .
Petronas will then charter these LNG vessels from MISC for 15 years, or maybe even more.
The new deal is practically an amendment to one that was signed two years ago. It novates or replaces a previous shipbuilding contract signed in 2013 between Petronas, MISC and Hyundai Heavy Industries (HHI).
In the old contract, Petronas ordered the five huge LNG vessels, with HHI as the shipbuilders, but bafflingly only appointed MISC as project manager and technical consultant.
Petronas wanted to operate the LNG carriers themselves, instead of relying on MISC’s expertise, as it had done so for decades.
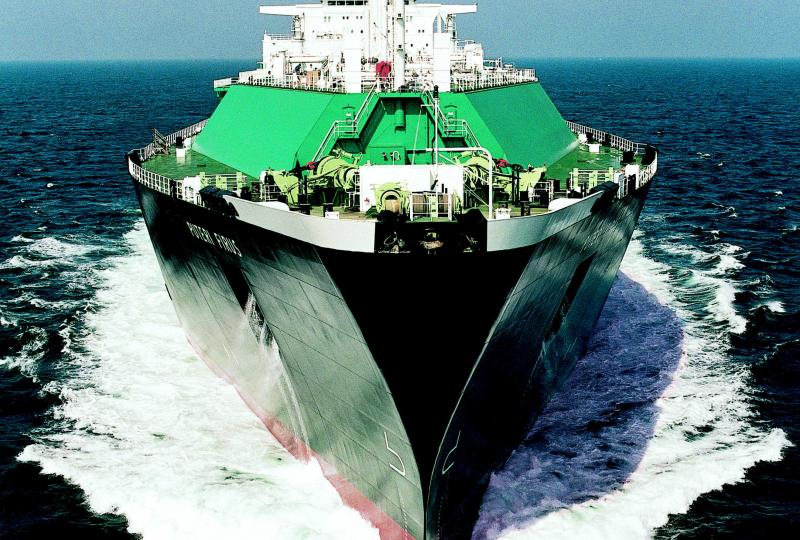 It was a strange decision, to say the least, considering that MISC has the world’s second largest fleet of LNG tankers and delivers an estimated 10% of the world’s LNG.
The fact that MISC is also a subsidiary of Petronas, who owns 62.7% of the company, made the move even stranger.
Was Petronas the oil giant trying to become its own shipping conglomerate, despite already owning a large chunk of MISC? Indeed, it was.
According to Petronas then, the decision was part of its strategy “to optimise the value of its LNG business”, justifying its decision to directly procure newly built LNG carriers by saying that the move “will allow Petronas to have direct access to LNG shipping capacity at the lowest possible costs.”
In other words, why can’t we have the cake and eat it too?
But why was Petronas presenting itself as a potential competitor to its own subsidiary MISC, that was already an established entity in the LNG carrier business? By leaving MISC to do what it did best, Petronas would have profited too, by virtue of its majority shareholdings in MISC.
The backdrop to the story is Petronas bungled attempt, earlier that year in January 2013, to take MISC private.
Petronas was deadlocked with MISC’s minority shareholders for over two months to seal the deal. The bone of contention was Petronas’ low valuation of MISC at RM5.50 per share. It required a 90% acceptance of outstanding shares that it did not own to delist MISC from the Bursa.
Many analysts then had pegged MISC’s fair value at RM6 to RM6.50, with some even rating it as high as RM8.00 per share based on future prospects.
 A lot rested on MISC’s two largest minority shareholders, namely Employees Provident Funds (EPF) and Permodalan Nasional Berhad (PNB) with 9.5% and 6.3% respectively. If either or both had refused to budge on Petronas’ offer, the deal would have been a non-starter.
Instead, it went down to the wire.
EPF controversially accepted Petronas’ final offer of RM5.50, but PNB did not. Other smaller minority shareholders held their ground and narrowly prevailed when the oil giant could only muster a final 86.07% stake.
Cue Petronas’ sudden eagerness to build its own fleet of LNG carriers, sidelining MISC in the process.
Many saw this as a warped kind of revenge by Petronas, sabotaging its own shipping-related subsidiary MISC for the oil giant’s failure to steamroll through minority shareholders in the aborted privatisation.
Fast forward 24 months later, MISC’s subsequent ascent in the stock market appears to have vindicated the minority shareholders’ refusal to take Petronas’ offer. In the last 12 months, its share price has risen steadily by more than 30%. Many analysts are targeting MISC’s share price to go beyond RM8.00.
And Petronas recent reversal in the RM4 billion LNG carrier deal, discarding its previous ambitions of developing its own LNG fleet, is a tacit admission of Petronas’ folly in dealing with MISC, as a subsidiary and resource.
Although the transfer was said to under consideration for some time, clearly the oil crisis has forced Petronas’ hands.
Which is not necessarily a bad thing.
Petronas has righted a wrong, albeit under trying times. Its newly appointed president and chief executive officer (CEO), Wan Zulkiflee Wan Ariffin, will have plenty of other opportunities for Petronas to make amends when he takes over this April, especially a gargantuan RM100 billion headache with its Canadian venture.
All Wan Zulkiflee needs to do is to constantly remind himself of the following mantra.
Rethink. Reprioritise. Reposition. Humble Pie.
GRRRRR!!!
You must be logged in to post a comment.